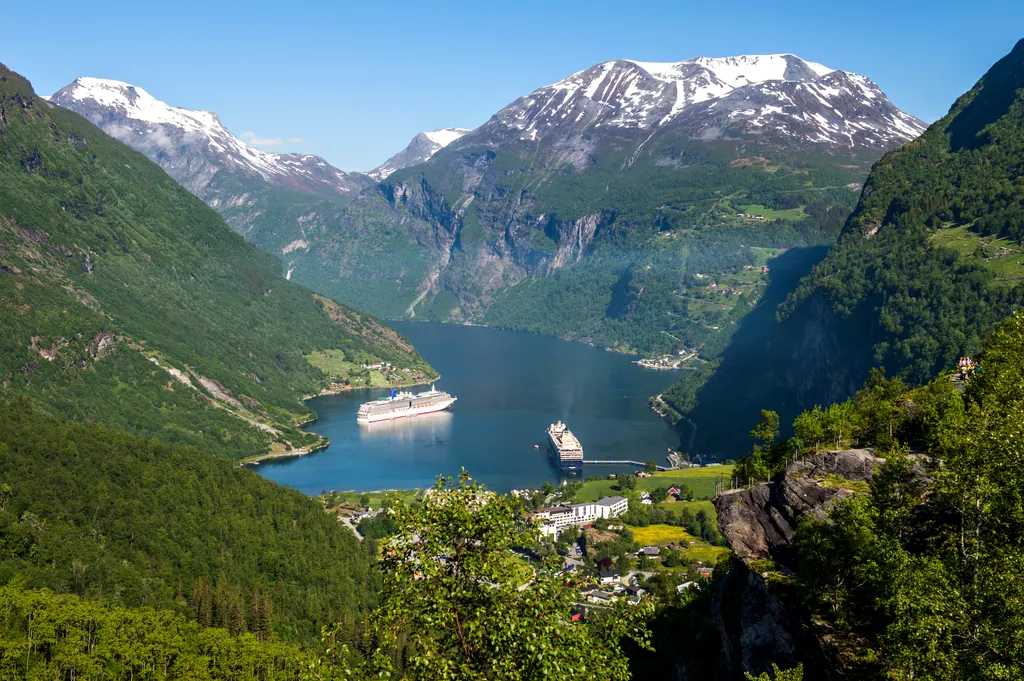
A cruise feels like the safest kind of trip to leave uninsured. Your cabin, meals and entertainment are paid for in advance, the ship carries its own doctor, and you never have to hunt for a hotel in a strange city. It is easy to assume the cruise line has the rest covered.
It does not, at least not in the way many first-time cruisers expect. The real question is not whether a cruise is risky, but which of your existing protections stop working once the ship leaves port. We looked at what the CDC, Medicare and the cruise lines themselves say, so you can decide what you actually need to buy.
What Happens If You Get Sick at Sea?
Every large cruise ship has a medical center, usually with a doctor and nurses on board. What surprises many passengers is that this care is not part of the fare. According to the CDC Yellow Book, the cost of medical treatment delivered on board a ship might not be included in the price of your ticket, which is exactly why the CDC suggests cruise travelers consider specialized insurance.
In practice, consultations, tests and medication on board are usually charged to your onboard account, the same account that holds your drinks and excursions. A simple visit for seasickness is not going to ruin you. A fall on a wet deck, a heart problem or a bad infection is a different story, because the ship's clinic is built to stabilize patients, not to treat them for days.
Does Your Health Insurance Work on a Ship?
This is the part most people never check. Many U.S. health plans offer little or no coverage outside the United States, and a cruise ship spends most of its time outside the country, even on a short Caribbean sailing from Florida.
Medicare is the clearest example. According to Medicare.gov, Original Medicare generally does not cover health care you get while traveling outside the United States. For cruise ships, it can cover medically necessary care only when the ship is in a U.S. port, or within six hours of arriving at or leaving one. Anything that happens on day three of a seven-day Caribbean cruise is usually outside that window. Some Medigap plans add limited emergency coverage abroad: according to the CDC, plans C, D, F, G, M and N may pay 80 percent of certain emergency costs after a $250 deductible, with a $50,000 lifetime maximum. Medicare Advantage plans vary, so read your plan documents. We cover the details in Does Medicare Cover International Travel?
Employer and marketplace plans differ widely. Some reimburse emergency care abroad after you pay the bill yourself, some only cover in-network care in the United States, and almost none pay for an evacuation. Call your insurer and ask three questions: Do you cover emergency care on a ship or in a foreign hospital? Do I have to pay first and file a claim? Do you cover medical evacuation?
Why Medical Evacuation Is the Big One
If you become seriously ill at sea, the ship may put you ashore at the next port, and from there you may need to get to a hospital that can treat you properly, sometimes in another country or back home. That is a medical evacuation, and it is where the large bills come from.
The CDC puts the cost of a medical evacuation at around $25,000 for transport within North America and over $250,000 for more distant and remote locations. A cruise to Alaska, the Norwegian fjords or Antarctica can put you a long way from a major hospital. Evacuation cover is one of the cheaper parts of a travel insurance policy, and it is the part we would least want to go without.
What Cruise Travel Insurance Usually Covers
A comprehensive travel insurance policy for a cruise typically combines several kinds of protection. The exact wording varies by insurer, so treat this as a checklist rather than a promise.
| Coverage | What it is for |
|---|---|
| Trip cancellation | Getting back prepaid, nonrefundable costs if you cancel for a covered reason, such as illness |
| Trip interruption | Costs if you have to leave the cruise early for a covered reason |
| Travel delay and missed connection | Hotel, meals or catching up with the ship if a covered delay makes you miss embarkation |
| Emergency medical | Treatment on board and in foreign hospitals |
| Medical evacuation | Transport to an appropriate hospital or home |
| Baggage | Lost, delayed or damaged luggage |
The CDC notes that comprehensive policies can cost up to 8 percent of the trip price with standard cancellation reasons, and up to 15 percent when you add cancel for any reason coverage.
Cruise Line Plans or Third-Party Insurance?
When you book, the cruise line will almost certainly offer its own protection plan. These plans are convenient, and some offer future cruise credits if you cancel. The trade-off is that the benefits are tied to that one company, cancellation payouts may come as credits rather than cash, and the medical and evacuation limits are sometimes lower than in a standalone policy.
A third-party travel insurance policy, bought from an independent insurer, is not tied to the cruise line. It can also cover the flights and hotel nights you booked separately to reach the port, which a cruise line plan may not. Compare both on three numbers: the emergency medical limit, the evacuation limit and how a cancellation is paid out.
When Insurance Matters Most
Some cruises carry more financial risk than others. Insurance is worth a closer look if:
- You are 65 or older, especially on Original Medicare, which leaves most care at sea uncovered.
- You have a pre-existing condition. Many policies cover it only if you buy within a short window after your first trip deposit. See our guide to travel insurance for pre-existing conditions.
- You are sailing far from home, such as an Alaska cruise, a repositioning cruise across an ocean or an expedition voyage.
- You sail in hurricane season. The Atlantic hurricane season runs from June 1 to November 30. Itineraries can change, and storms can delay flights to the port.
- You are flying in on the day of departure. The ship does not wait for late passengers. Flying in the day before is the cheapest insurance there is, but missed connection cover helps if things still go wrong.
Our Take
For a short, inexpensive cruise, if your own health plan clearly covers emergencies abroad, you might decide to skip cancellation cover and simply accept the risk of losing the fare. What we would not skip is medical and evacuation coverage, because that is where a single bad day at sea can turn into a five- or six-figure bill.
Buy early, ideally soon after your deposit, read the exclusions, and check that the policy names cruises specifically. You will find more planning advice under cruises and travel insurance.
Frequently asked questions
Is medical care on a cruise ship free?
No. Onboard medical care is usually not included in the cruise fare, and consultations, tests and medication are typically charged to your onboard account.
Does Medicare cover you on a cruise?
Only in limited cases. Original Medicare can cover medically necessary care when the ship is in a U.S. port or within six hours of arriving at or leaving one. Care farther out at sea is generally not covered.
Is cruise line insurance or third-party insurance better?
It depends on the policy. Third-party plans are not tied to one cruise line and can cover separately booked flights and hotels, while cruise line plans are convenient but may pay cancellations as cruise credits. Compare medical and evacuation limits.
How much does a medical evacuation cost?
According to the CDC, a medical evacuation costs around $25,000 within North America and can exceed $250,000 from distant or remote locations.